What Is an 80/10 Piggyback Loan in Lancaster PA, and Who Qualifies?
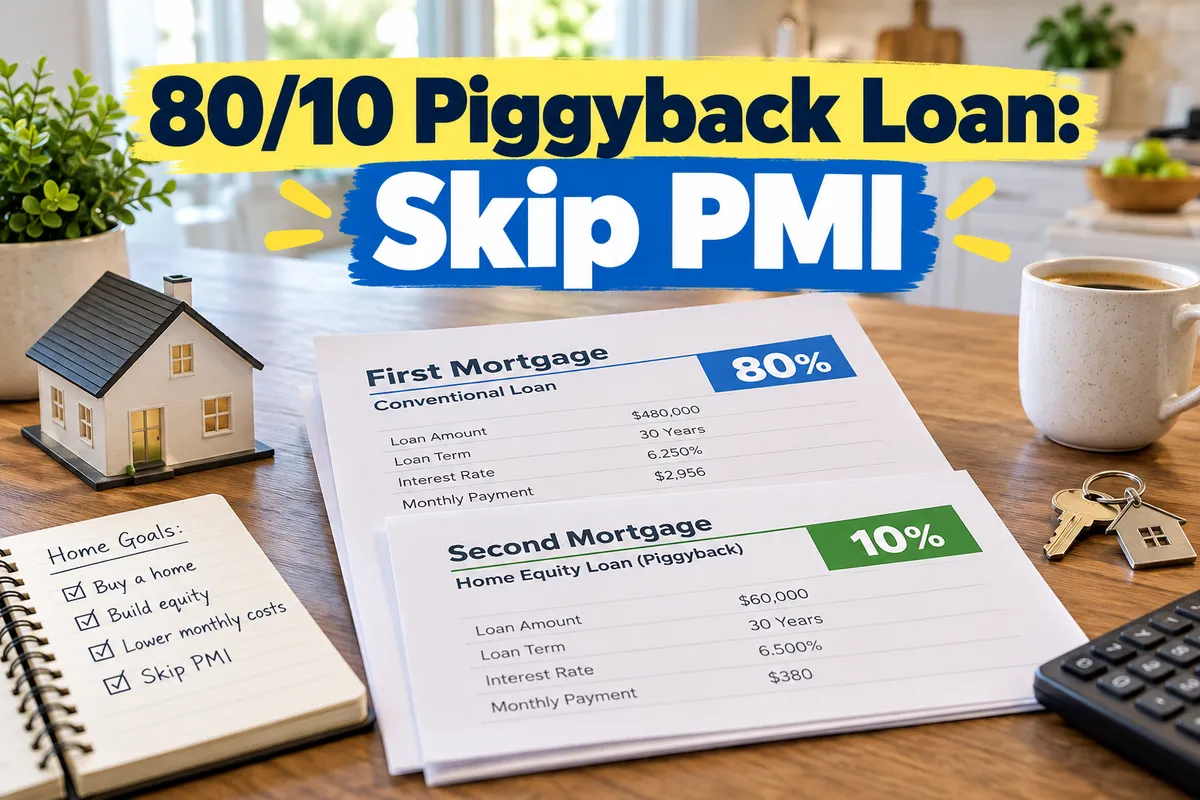
An 80/10 piggyback loan lets you buy a Lancaster PA home with 10% down and skip private mortgage insurance. You take a first mortgage for 80% of the price, a second loan for 10%, and you bring the last 10%. For the right buyer in Lancaster County, it can beat paying PMI. For the wrong buyer, it's just a second bill with a variable rate.
Here's how it works, who it fits, and the real math on a Lancaster-priced home.
How an 80/10/10 piggyback loan works
The name tells you the structure. You'll also hear it called an 80/10/10.
80%: a regular first mortgage, usually a 30-year fixed conventional loan.
10%: a second loan that "piggybacks" on the first. It's often a home equity line of credit (HELOC) or a fixed-rate home equity loan, closed at the same time as your purchase.
10%: your down payment.
Why bother? Because on a conventional loan, PMI kicks in when you borrow more than 80% of the price. PMI is insurance that protects the lender, not you. With a piggyback, your first mortgage stays at 80%, so there's no PMI on it. You pay interest on the second loan instead.
It's one of my favorite tools for buyers who have real savings but don't want to wait years to hit 20% down.
The numbers: piggyback vs. PMI on a Lancaster County home
Let's use a $370,000 home. That was the Lancaster County median sold price in September 2026, per Lancaster County Association of Realtors data reported by LNP | LancasterOnline.
For rates, I'm using 7.40%, Freddie Mac's 30-year average for the week of October 15, 2026, and 7.34%, Bankrate's national average HELOC rate as of October 14, 2026. Your rates will depend on your credit, your lender and the loan. A second loan that takes you to 90% can price higher than that HELOC average, so get real quotes. Taxes and homeowners insurance come on top of everything below.
Option 1: 10% down with PMI
Down payment: $37,000
Loan: $333,000 at 7.40%, about $2,306 a month in principal and interest
PMI: Freddie Mac says to expect roughly $30 to $70 a month per $100,000 borrowed. On $333,000, that's about $100 to $233 a month.
Total: about $2,406 to $2,539 a month
Option 2: 80/10/10 piggyback
Down payment: $37,000
First mortgage: $296,000 at 7.40%, about $2,049 a month
Second loan: $37,000. Interest-only at 7.34% is about $226 a month. Paid down over 20 years at that rate, it's about $294 a month.
Total: about $2,275 to $2,344 a month
So in this example, the piggyback runs roughly $60 to $260 a month cheaper, depending on how your PMI prices out and how the second loan is set up. If your credit gets you cheap PMI, the gap shrinks. If PMI prices high, the piggyback wins big.
One more thing to weigh. PMI goes away once you build enough equity. The second loan doesn't disappear. You pay it off, either over time or in a lump sum. That's not a deal-breaker. It's just the trade.
Who qualifies for a piggyback loan in Lancaster PA?
There's no single rulebook, because you're really qualifying for two loans, and each lender sets its own guidelines. In general, expect lenders to look closely at:
Credit. You're carrying two payments, so the second-loan lender will look hard at your score and history.
Debt-to-income ratio (DTI). That's your monthly debt payments divided by your gross monthly income. Both loan payments count.
Cash. You still need the 10% down, plus closing costs on both loans, plus reserves.
Property type. Owner-occupied single-family homes are the easiest fit. Ask before you assume it works on a condo or investment property.
Not every lender offers piggybacks, so it pays to shop. Ask local banks and credit unions as well as mortgage companies.
When a piggyback makes sense (and when it doesn't)
It fits when:
You have about 10% saved and the PMI quote on your loan is high.
You're a move-up buyer. You buy the new place with a piggyback, then pay off the second loan when your current Lancaster home sells. I walk through a similar play in buying before you sell in Lancaster.
You expect income growth, a bonus or other cash you'll use to knock out the second loan in a few years.
Think twice when:
You're stretching. A variable-rate HELOC payment can rise.
Your PMI quote is already low. Then the simpler loan may be the better deal.
You'd drain your savings to make it work. Keep a cushion.
And if you don't have 10%, that's fine. You've got other doors. I break down the low-down-payment options in how much down payment you need in Lancaster, and the trade-offs between loan types in FHA vs conventional in Lancaster.
Don't let 7% rates freeze you
Rates above 7% scare people off. I get it. But don't try to time the market. Run your numbers. If the payment works for your budget today, you start building equity now, and you can look at refinancing if rates come down later. A piggyback is one more way to make today's numbers work without waiting years to save 20%.
There's almost always a structure that gets you in the door. Piggybacks, seller assist, PHFA help and gift funds can even work together. The trick is pricing each option side by side before you write an offer.
Frequently asked questions
Is an 80/10/10 loan the same as a second mortgage?
Yes. The "10" is a second mortgage, recorded behind your first. It might be a HELOC with a variable rate or a home equity loan with a fixed rate.
Can I pay off the second loan early?
Often, yes. Many buyers pay it down with a bonus, savings or the sale of their old home. Ask each lender about prepayment terms and any fees for closing the line early.
Is a piggyback better than PMI?
It depends on your PMI quote and your second-loan rate. Ask your lender to price both options on the same home and compare the full monthly payment and total cost.
Do piggyback loans work with first-time buyer programs?
Sometimes, but not always. Assistance programs have their own rules about second loans. Ask your lender before you plan on stacking them.
Want to see if a piggyback beats PMI for you?
If you've got some savings but the thought of PMI, or waiting years to hit 20%, has you stuck, let's talk it through. Book a free, no-pressure call and we'll price out a piggyback against your other options on a real Lancaster home, so you know exactly which path costs less.
Still deciding where in the county you want to land? Grab my free Living in Lancaster guide.
About Albert Linsdell
Albert Linsdell is a Lancaster, PA real estate agent helping buyers and sellers across Lancaster County, including Lancaster City, Manheim Township, Lititz, Ephrata and Mount Joy. He's known for numbers-first pricing, creative financing strategies, and a trusted contractor network that helps sellers get top dollar. He's rated 5 stars across 22 Google reviews. Book a call with Albert.